What Panama’s Shift Off the EU Tax Blacklist Teaches Property Owners
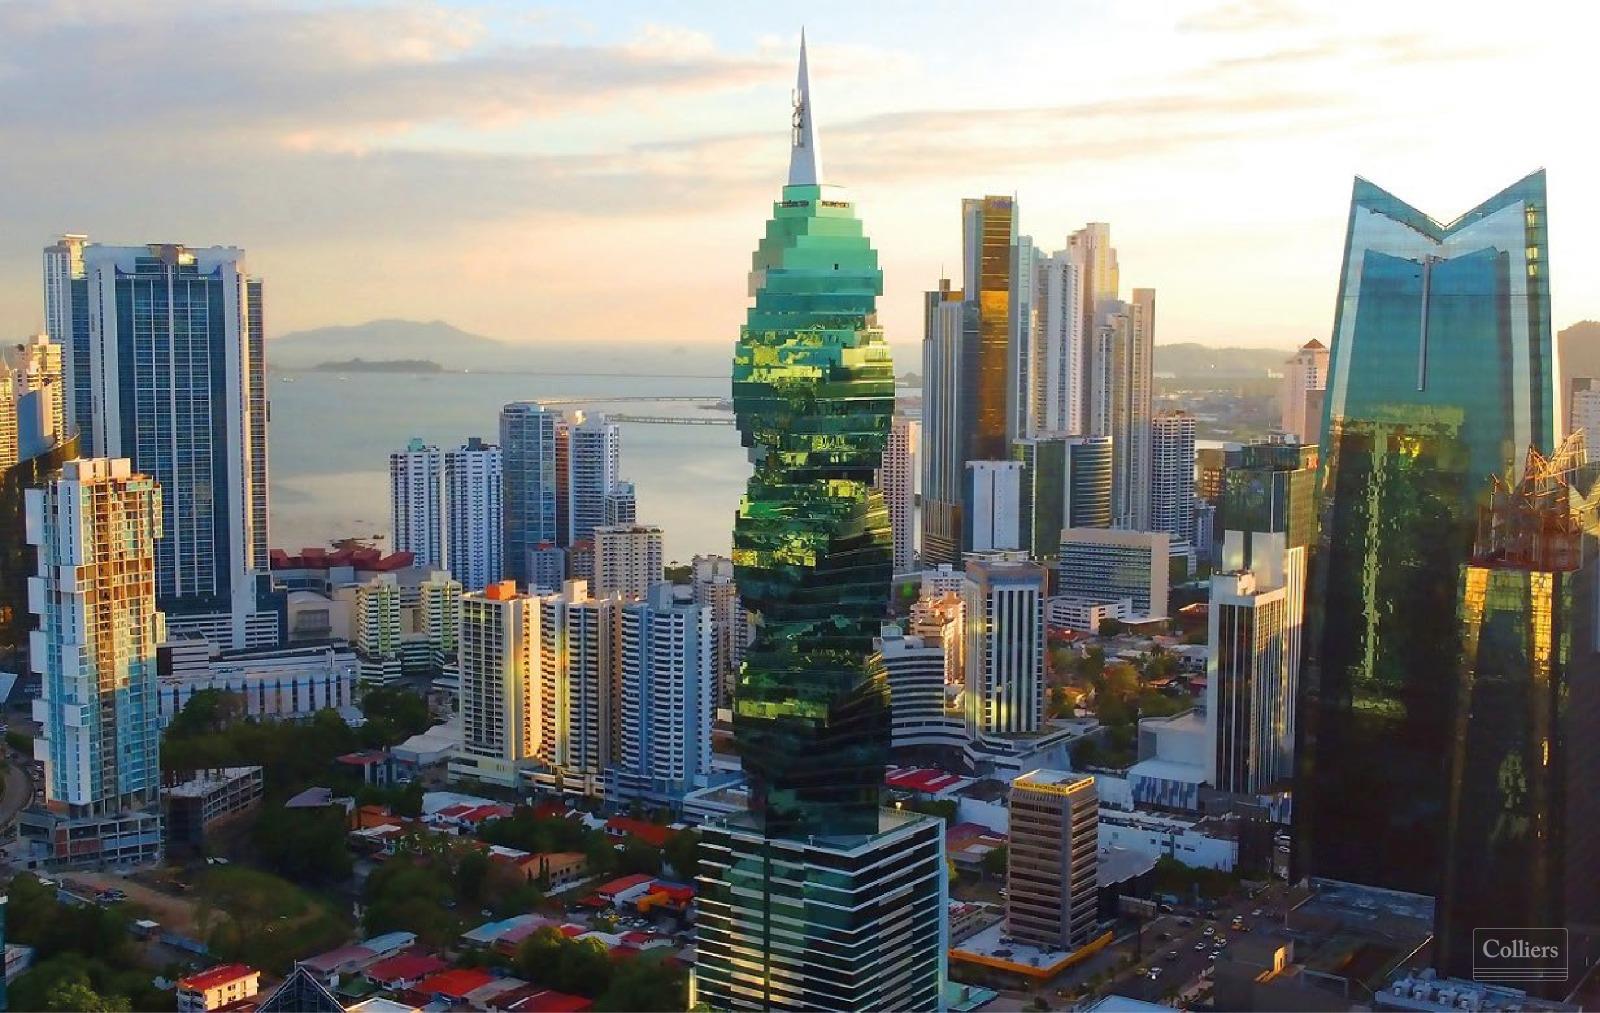
The European Union took Panama off its list of non-cooperative jurisdictions for tax purposes, and half the emails I got that week came from property owners who read the headline as “everything is fine now.” It isn’t. A blacklist removal changes how banks and counterparties look at you. It does nothing about the appraisal notice sitting on your desk with a number you don’t recognize.
Here’s what that gap actually looks like in practice. Cross-border ownership means you’re juggling two, three, sometimes four separate valuation systems, each with its own filing calendar, its own definition of market value, and its own idea of what counts as evidence. Miss one window because you were busy with the other country’s paperwork, and you’ve handed away a year of savings without a single phone call. That’s the part nobody puts in the press release.
Fifty years of combined market cycles is roughly what it takes to read a Latin American valuation the way locals do, which is why owners with holdings in Texas and abroad tend to hand the domestic side to property tax consultants texas while they wrestle with their offshore filings. Splitting the workload that way isn’t laziness. It’s triage.
Why a Blacklist Removal Is a Signal, Not a Deadline
People treat these lists like a switch that flips from danger to safety. They’re closer to a credit score. Getting removed takes you out of the penalty box with banks and institutional counterparties, but it doesn’t revalue a single square meter of what you own. A warehouse in Houston and a rental in Panama City both get assessed on local rules that were written long before any EU council meeting happened.
According to the OECD, tax transparency standards have been tightening across most major economies for years, which is why jurisdictions keep adjusting their disclosure and filing expectations rather than standing still. That’s the real takeaway. The paperwork gets more demanding, not less, even when your country’s reputation improves.
So what do you do with that? You stop reading list news as a plan and start reading it as a reminder to recheck your calendars. I’d take a boring spreadsheet over a triumphant press release any day, because the spreadsheet is what actually protects your cash.
What Cross-Border Owners Keep Getting Wrong
The single most common mistake is assuming value travels. It doesn’t. A property that appraises at one figure in one jurisdiction can land at a wildly different number next door, using the same building, same tenants, and same income. Local assessors weigh income approach, sales comparables, and replacement cost differently, and the weighting shifts by property type.
You’ll also hit these recurring problems:
- Filings stacked on top of each other across two or three deadlines in the same quarter
- Notice letters going to an address you stopped using two ownership changes ago
- Business personal property returns filed in the wrong jurisdiction, or not at all
- Appeal windows that are shorter than the time it takes to gather your own records
Notice how none of these are about tax law. They’re logistics. The owners who save money aren’t the ones who know the most statutes. They’re the ones who never miss a date and never show up to a hearing with a shoebox of receipts.
I’ve watched owners win an appeal on a strong income argument, then lose the next cycle purely because the notice went to a decommissioned PO box. That’s not bad luck. That’s an address list nobody updated.
The Two-List System I’d Actually Use
Here’s a framework I’ve found holds up across jurisdictions. I call it the two-list system, and it’s deliberately unglamorous.
List one is your deadlines. Every jurisdiction where you hold property, every filing date, every appeal window, every payment due date. One row per property. No exceptions, no “I’ll remember.”
List two is your evidence. For each property, the documents that prove your value argument: leases, occupancy records, repair invoices, comparable sales, income statements. Filed before you need them, not the week a hearing gets scheduled.
The two connect in one place: the moment a notice arrives, you check list one for the appeal deadline, then check list two for what you can actually prove. If list two is empty, you don’t have an appeal. You have a complaint.
A concrete example. Say you own a mid-size office building and a residential rental in two different states. Your office notice arrives with a value increase you disagree with. Under the two-list system, you’ve already got current leases and a vacancy history on file, so your protest goes in with real numbers attached. Meanwhile your residential notice arrives three weeks later, and because the residential deadline sits outside the window you planned for, you would have missed it entirely without the calendar. That’s the entire value of the system. It catches the thing you weren’t looking at.
This is also where most owners underestimate how much the professional side costs versus saves. A consultant who already knows the local assessor’s methodology and hearing process is worth more than a stack of generic templates, because the argument has to fit the forum.
Where Stability Actually Comes From
Reputation shifts and rule changes get the headlines, but the underlying conditions that protect property owners are boring and slow. According to the World Bank, property registration systems and legal certainty are among the strongest predictors of whether an owner can defend their investment across borders over time. Strong registries, clear title, reliable records. That’s what you’re really betting on.
Which means your own record-keeping is part of the same story. If your title documents, ownership structure, and valuation evidence are all current and in one place, you’re operating like a well-run registry. If they’re scattered across three email accounts and a storage unit, you’re operating like a jurisdiction nobody trusts.
The European Union publishes the criteria behind its tax lists, and reading them once tells you something useful: these reviews reward consistency and disclosure, not size or geography. The same trait rewards property owners. Consistency in filing, consistency in records, consistency in showing up on time.
Your Practical Checklist Before Next Assessment Season
- Pull every notice and confirm the mailing address on file for each property.
- Build the deadline list for every jurisdiction you own in, current year and next.
- Gather income, lease, and occupancy records for each property into one folder.
- Identify which properties have a defensible value argument and which don’t.
- Decide, property by property, whether you handle the protest or bring in someone local.
- Set a reminder thirty days before each filing window opens, not the day it closes.
Do those six things and the blacklist headlines stop mattering so much. You’re no longer reacting to news. You’re running a schedule.
What to Do With This
Panama coming off the EU list is genuinely good news for anyone holding assets there, and it may loosen some doors with banks and institutional partners. It won’t lower a single assessment, and it won’t extend an appeal deadline by one day. Those two jobs belong to your calendar and your records.
So here’s the question worth sitting with this week: if a notice arrived tomorrow for your most valuable property, could you name the appeal deadline and produce your evidence within the hour? If the answer is no, the list news isn’t your problem. The gap between list one and list two is.