Panama Still Faces a Key Review in 2027 in the Process of Being Removed from the European Union’s Tax List.
Panama hopes to take another step toward being removed from the tax list following the approval of the Law on Economic Substance. However, the country must pass a review on tax information exchange in 2027 to definitively complete the process.
Panama is making progress in the process of being removed from the European Union’s List of Non-Cooperative Jurisdictions for Tax Matters, commonly known as the list of tax havens, but still has a key evaluation pending related to the exchange of tax information. Yasmín del Carmen González pictured below, head of International Fiscal Strategy at DEFFI of the Ministry of Economy and Finance (MEF), explained the “Law of Economic Substance: from regulation to implementation”, that some evaluations are still needed before being completely free of this list.
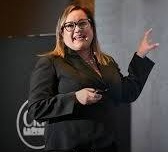
González pointed out that the approval of Law 526 on Economic Substance and its regulations allows Panama to address one of the criteria that kept it under observation by the European Union, related to fair taxation and the requirement of real economic activity for certain entities that receive passive income from foreign sources. However, she clarified that the process is not yet complete. The official explained that Panama still has pending the criterion related to the exchange of information on request, in which the country currently has a rating of “partially compliant”, while the European Union requires an evaluation of “fully compliant”.
“Today we have a rating of partially compliant and the European Union requires a rating of fully compliant.” says Yasmín González, Head of International Fiscal Strategy at the MEF’s Deefi.
To make progress on this point, Panama requested an in-depth review from the OECD’s Global Forum on Transparency and Exchange of Information for Tax Purposes, a request that has already been accepted. “We succeeded in giving Panama the opportunity to be re-evaluated,” González emphasized.
Yasmín del Carmen González, head of International Tax Strategy at DEFFI, Ministry of Economy and Finance.
The review is planned for the first three months of 2027, although there is no specific date yet. “The in-depth review of the exchange request will take place soon, in the first three months of 2027. There is still no firm date; it has not been granted to us at this time,” she explained. The result of this evaluation will be crucial to completing the process. “If we manage to obtain a rating of being highly compliant, then we will have the definitive closure of the process of leaving the European Union’s list of non-cooperative jurisdictions in tax matters,” she said. González also identified three areas that will be relevant in this evaluation: accounting records, information on beneficial owners, and the ability of Panamanian authorities to access information and respond to requests from other jurisdictions.
In the case of accounting records, he highlighted that the level of compliance is currently around 80%. “Today, compliance on this issue is at 80%,” she said. Another point that must be kept under control is response times. The international standard establishes a 90-day period for responding to information requests from other jurisdictions. González explained that the greater availability of accounting records has allowed for improved responsiveness from the tax administration. Even if Panama manages to make progress in its situation with the European Union, González insisted that international monitoring will continue throughout the process. The official also indicated that the implementation of the Economic Substance Law will be monitored. “We will be monitoring the effective implementation of the standard.” says Yasmin del Carmen Gonzalez.
What Changes for Businesses with the Economic Substance Act?
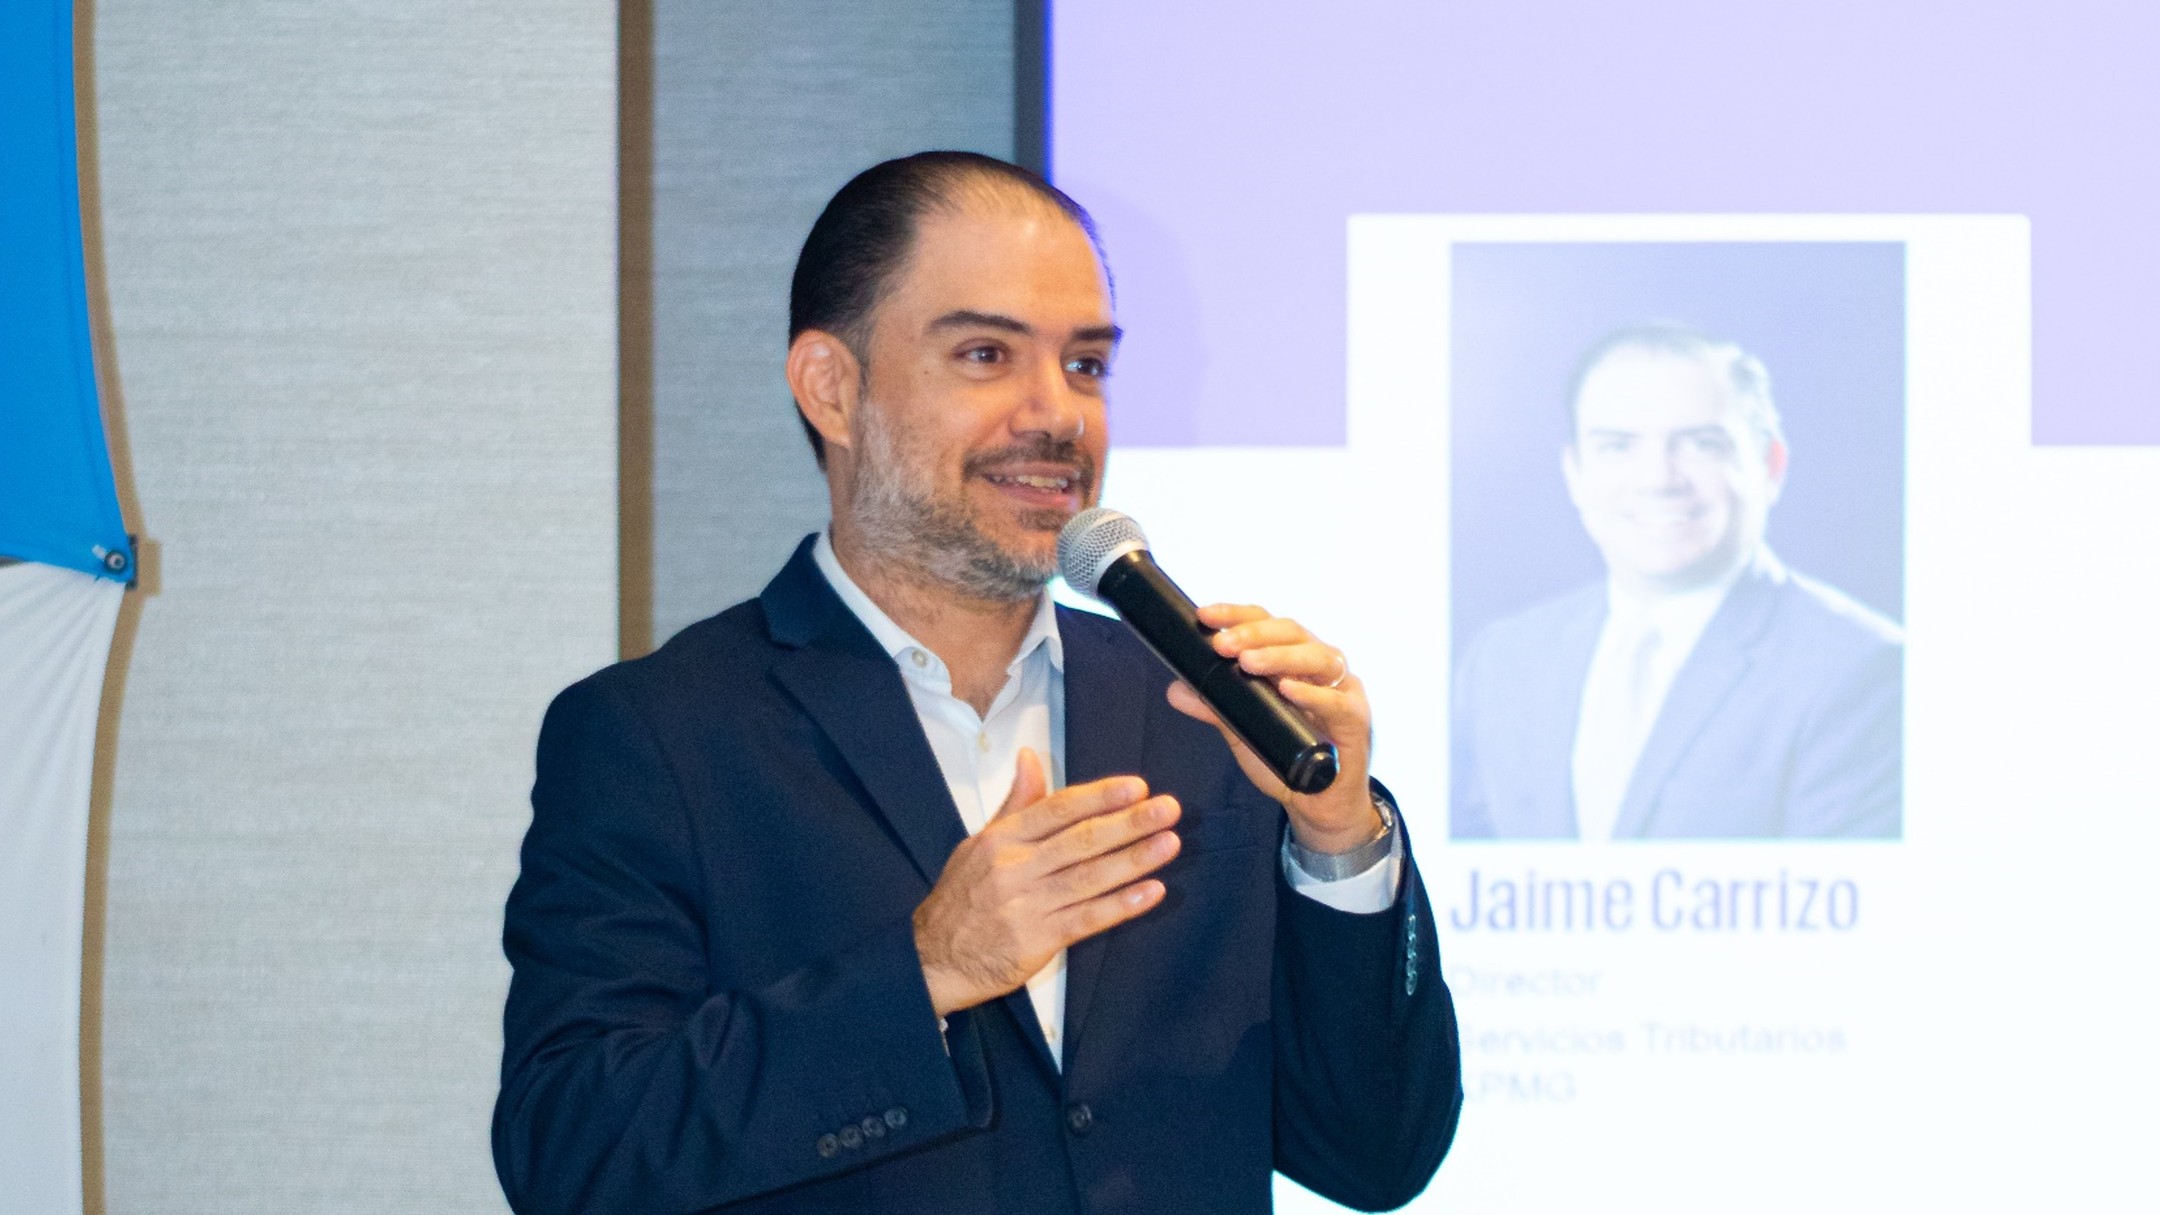
During the same meeting, Jaime Carrizo pictured above, partner of Tax Services at KPMG Panama, and Juan Raúl Sosa Vallarino pictured below, partner at Fabrega Molino, explained some of the main aspects that companies should consider.
- This does not apply only to holding companies:
Carrizo clarified that the rule may apply to entities incorporated or domiciled in Panama that are part of multinational groups and receive passive income from foreign sources.
“The scope of this regulation is not designed to focus on holding companies, but rather encompasses a much broader universe.” says Jaime Carrizo, Tax Services Partner at KPMG Panama.
- Six types of rents are under analysis:
The law applies to income such as dividends, interest, royalties, capital gains, returns on real estate and returns on movable property.
Three Pillars of Compliance.
Juan Raúl Sosa Vallarino, partner at Fabrega Molino, explained that the entities reached must have adequate human resources and facilities, demonstrate strategic decision-making in Panama, and maintain operating costs and expenses linked to their activity.
Documentation will be key: Companies must keep documents that demonstrate their economic substance for a minimum of five years.
Decisions must be made in Panama: The regulations stipulate at least two annual meetings linked to strategic decisions and risk-taking.
Outsourcing has limits: Sosa summarized this principle with the phrase: “You outsource the hands, not the decisions.”
“Companies will have to keep, for a minimum of 5 years, all the documentation that gives them the substance or that fundamentally proves the substance in the future.” says Juan Raúl Sosa Vallarino, partner at Fabrega Molino.
The application will begin in 2027: The regime will come into effect on January 1, 2027, and the first sworn statement will be submitted in 2028.